How Much Is My Personal Injury Case Worth in South Carolina?
September 27, 2026What Happens If the Driver Who Hit Me Has No Insurance?
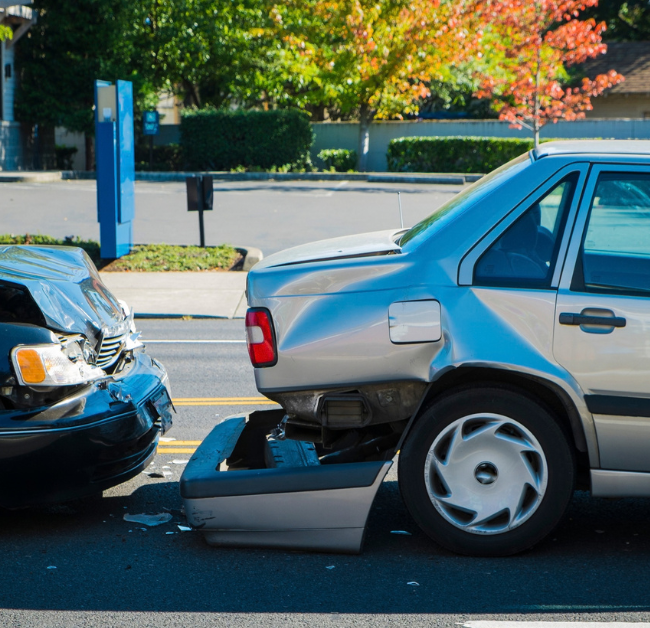
Finding out the driver who hit you does not have insurance can make an already stressful accident feel even worse. You could be dealing with medical bills, car repairs, missed work, and pain while wondering who is going to pay for any of it. The good news is that an uninsured driver accident in South Carolina does not automatically leave you without options.
South Carolina requires auto insurance policies to include uninsured motorist coverage, often called UM coverage. This coverage exists to protect you when the person who caused the crash has no insurance or, in some cases, when a hit-and-run driver cannot be identified. The details depend on the accident and your policy, but the first step is understanding what coverage you already have.
What Does Uninsured Motorist Coverage Do in South Carolina?
Uninsured motorist coverage can step in when the driver who caused your accident has no liability insurance. Instead of depending only on that driver’s personal ability to pay, you can look to the UM coverage under your own auto policy for help with certain losses.
South Carolina requires at least $25,000 in bodily injury coverage for one person, $50,000 for bodily injury to two or more people in one accident, and $25,000 for property damage. Some drivers carry higher limits. Depending on your policy and the facts of the crash, UM coverage could help with medical bills, lost income, pain and suffering, vehicle damage, and other losses that South Carolina law allows.
Using your own insurance does not mean you caused the accident. UM coverage is there for exactly this kind of situation, so do not feel like filing a claim means you are taking responsibility for someone else’s mistake.
What Is the Difference Between Uninsured and Underinsured Motorist Coverage?
Uninsured and underinsured coverage sound similar, but they solve different problems. Uninsured motorist coverage applies when the at-fault driver has no usable liability insurance, while underinsured motorist coverage can help when that driver has insurance but not enough to cover the full amount of your losses.
For example, someone could suffer serious injuries in a crash caused by a driver who carries only the minimum amount of liability insurance. If the medical bills, lost wages, and other damages are much higher than those policy limits, underinsured motorist coverage, or UIM coverage, on the injured person’s own policy could become important.
South Carolina requires insurance companies to offer UIM coverage, but drivers do not have to buy it. That is why I tell people not to rely on memory after a serious crash. Pull out the policy, look at the declarations page, and see exactly what coverage and limits you have.
What If the Driver Left the Scene of the Accident?
Hit-and-run accidents can also involve uninsured motorist coverage, but South Carolina has special rules when nobody knows who the other driver was. If someone leaves the scene, report the accident to law enforcement as soon as reasonably possible and start preserving evidence right away.
These cases can depend heavily on proof of what happened. Physical contact with the unknown vehicle, an independent witness, dashcam footage, traffic cameras, or other recordings can become important. For example, if another vehicle forces you off Highway 17 without actually hitting your car, the lack of contact does not always end the claim, but strong evidence becomes even more important.
If you are involved in a hit-and-run in Myrtle Beach or anywhere along the Grand Strand, take photos if you can do so safely, write down what you remember, and get contact information from any witnesses. The sooner you preserve that evidence, the better chance you have of showing how the crash happened.
Can I Sue the Uninsured Driver Personally?
You can sometimes pursue a claim against the person who caused the accident even if that driver did not have insurance. The bigger problem is whether that person has enough income or assets to actually pay a judgment.
That is one reason UM coverage matters so much. A legal right to recover money from someone does not mean the person has the money to pay it, so your own insurance coverage can become the more practical path. An attorney can review the available insurance, the driver’s situation, and any other possible sources of recovery before helping you decide what makes sense.
Does My Own Insurance Company Automatically Pay My Claim?
No. Even though UM coverage comes from your own policy, your insurance company still has the right to investigate the claim and ask for proof of what happened. The insurer can look at who caused the accident, the nature of your injuries, your medical treatment, your lost income, the damage to your vehicle, and the amount of your other losses.
That means you should treat an uninsured motorist claim just as seriously as a claim against another driver’s insurance company. Keep your medical records, bills, repair estimates, wage information, photos, witness details, and other documents connected to the crash. When an adjuster asks questions, answer truthfully based on what you know, but do not guess about fault, future medical care, or how quickly you will recover.
What Should I Do After an Accident With an Uninsured Driver?
Start with the same basic steps you would take after any serious crash. Call law enforcement, get medical care when you need it, take photographs if you can do so safely, and get the names and contact information of witnesses. You should also collect the other driver’s name, contact information, vehicle information, and insurance details even if they claim they do not have coverage.
After the crash, report it to your own insurance company and ask for a copy of your policy or declarations page if you do not already have one. Look for uninsured motorist coverage, underinsured motorist coverage, medical payments coverage, collision coverage, and the limits that apply to each one. If the insurance questions become confusing or your injuries are serious, getting legal advice early can help you avoid making decisions before you understand your options.
Who Pays My Medical Bills While the Claim Is Pending?
An uninsured motorist claim does not always mean your auto insurer will pay every medical bill as soon as it arrives. Health insurance can still play an important role, and medical payments coverage on your auto policy could also help with certain expenses if you purchased it.
Later, your UM claim could include medical expenses that South Carolina law allows you to recover from the at-fault driver. Health insurance payments, medical liens, reimbursement issues, and other factors can affect the final numbers, so the process can become more complicated than simply adding up every bill.
The most important thing is to get the medical care you need and keep good records of your treatment. Do not put off care simply because you are unsure which insurance company will ultimately pay.
What If I Was Hit While Visiting Myrtle Beach?
You do not have to live in South Carolina for an uninsured-driver accident here to create a South Carolina legal issue. Visitors get into crashes every year on Highway 17, Highway 501, Highway 31, Highway 544, and local Grand Strand roads, and many of them have insurance policies issued in another state.
If the driver who hit you has no insurance, your own policy could become part of the claim while South Carolina law still affects the accident itself. When the driver, vehicle, insurance policy, and crash involve more than one state, the legal and insurance questions can get complicated quickly. A South Carolina attorney can help you sort out which rules and policies apply.
No Insurance Does Not Always Mean No Recovery
When you discover that the driver who caused your crash has no insurance, it is understandable to worry that there will be no way to recover your losses. South Carolina’s required uninsured motorist coverage exists because uninsured drivers are a real risk, and your own policy could provide an important source of protection.
The next step is to find out what coverage you have, preserve the evidence from the crash, document your injuries and financial losses, and understand what your policy actually provides. If you are dealing with an uninsured driver accident in South Carolina, Winslow Law can review the accident, the available insurance, and the facts of your situation so you have a clearer picture of your options.
If you’d like a no-obligation consultation with a local community lawyer, contact Winslow Law to discuss your accident and your insurance coverage. This article provides general legal information, not legal advice, and does not create an attorney-client relationship because every accident and insurance policy is different.
Winslow Law—Committed counselors for our clients and community.
FAQs
1. What Happens if Someone Hits Me and Does Not Have Car Insurance in South Carolina?
Your own uninsured motorist coverage could provide compensation when an uninsured driver causes the accident. South Carolina requires auto policies to include minimum UM coverage, but the amount available and what it covers depend on your policy, the facts of the accident, and the damages you can legally prove.
2. What if the Other Driver Has Insurance but Not Enough to Pay for My Injuries?
Underinsured motorist coverage could become important when the at-fault driver has insurance but not enough to cover your losses. South Carolina requires insurers to offer UIM coverage, but drivers do not have to buy it, so you should check your policy to see whether you have that protection and what limits apply.
3. Does Uninsured Motorist Coverage Apply to a Hit-and-Run Accident?
It can, but South Carolina has special requirements when the driver cannot be identified. Reporting the crash quickly and preserving evidence such as witness information, photos, video, or proof of contact with the unknown vehicle can become very important when the insurance company investigates the claim.